STORM DAMAGE & INSURANCE CLAIMS IN MARYLAND A storm passed. Let’s see how your roof held up.
You don’t have to figure it all out alone. Start with an honest roof inspection and a clear conversation about what comes next.
- Honest findings. No pressure. If we don’t find visible storm damage, we’ll tell you.
- You stay in control. Requesting an inspection doesn’t file a claim or commit you to repairs.
- Already filed a claim? You can still request an inspection.
- Free, no-obligation inspections
- Locally owned in Silver Spring
- MHIC #164924
AN HONEST SECOND OPINION FIRST
Your roof. Your home. An honest answer.
Insurance claims can be confusing. Between inspections, adjusters, deductibles and paperwork, it’s hard to know whom to trust.
We think homeowners deserve clear answers, not sales pressure. Our job is to document the condition of your roof, explain the repairs it may need and help you understand the roofing side of the insurance process.
We won’t recommend filing a claim just to sell you a roof.
HOW THE INSURANCE CLAIM PROCESS WORKS
Six steps. Clear communication. No unnecessary surprises.
Schedule your roof inspection
We examine your roof for signs of wind, hail and other damage. We document what we find and explain whether it looks consistent with storm damage or normal wear and tear.
Review your findings and options
We walk you through the photos and explain the roofing work, if any, that may be needed. You decide whether to contact your insurance company and open a claim.
File your claim with your insurer
If you choose to file, you contact your insurance company. We can provide our inspection documentation to help you describe the damage accurately. Your insurer determines coverage.
Insurance adjuster inspection
Your insurer may send an adjuster to inspect the property. When appropriate, we can be there to point out the roofing findings we documented.
Review the repair scope and estimate
If the claim is approved, we compare the insurer’s roofing scope with the work needed. If something appears missing, we can provide more photos, measurements and a contractor’s estimate for their consideration.
Restore your roof
Once the work is authorized and you’ve chosen WeRoof, we review materials, pricing and schedule with you, complete the agreed work and provide the closeout documentation.
Not every roof needs an insurance claim. Sometimes a straightforward repair is the better option. We’ll explain what we find so you can make an informed decision.
WHAT TO LOOK FOR
What does storm damage look like?
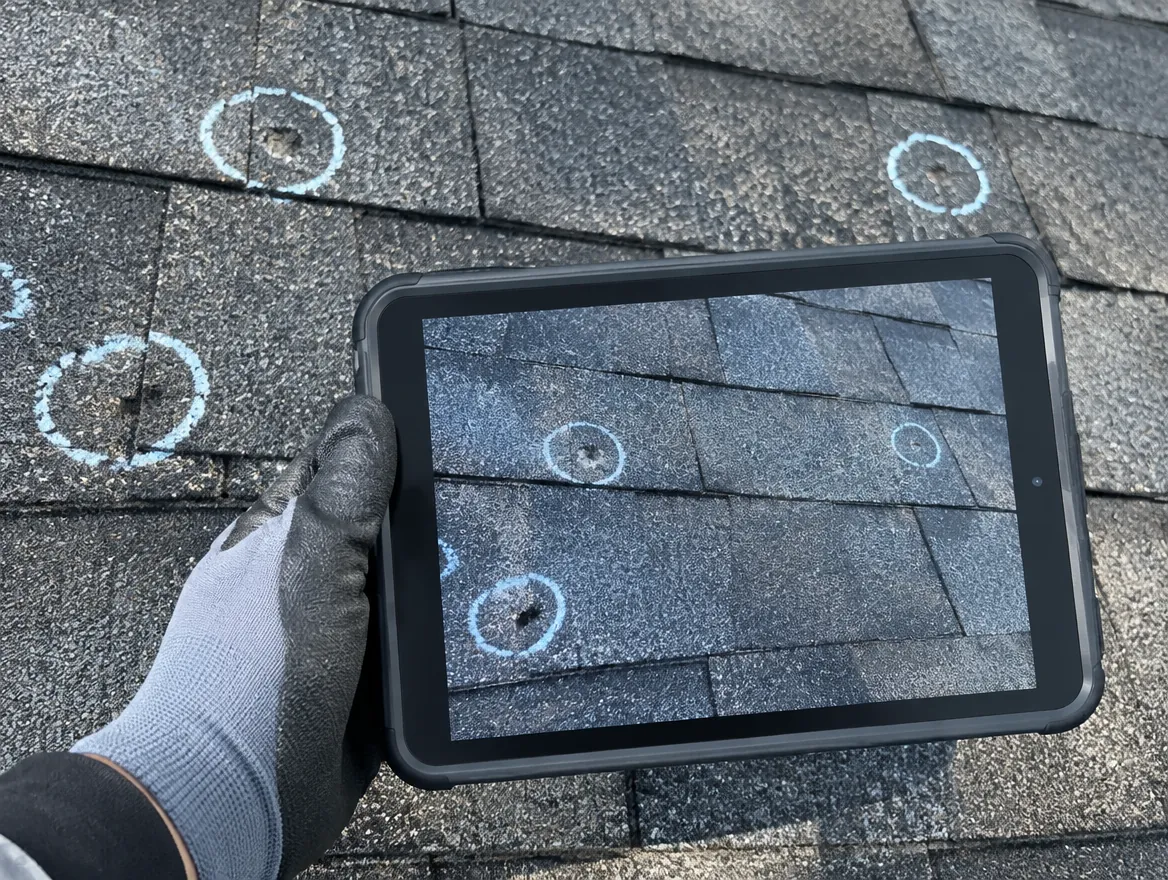
- Wind damage Lifted, creased, torn or missing shingles.
- Hail damage Impact marks, bruising and loose granules.
- Roof leaks Water getting in, with a cause that needs to be traced.
- Gutter & exterior damage Dents and damage to gutters, siding or flashing.
Visible signs don’t automatically establish insurance coverage. Damage has to be evaluated in context and under your specific policy.
OUR ROLE, CLEARLY
What we do, and what we don’t.
We do
- Inspect your roof and document visible damage
- Explain repair options in plain language
- Provide photos, measurements and a written estimate
- Complete the roofing work you approve
We don’t
- Guarantee claim approval or coverage
- Negotiate your settlement or act as a public adjuster
- Waive or absorb your deductible
- Pressure you into filing a claim
Current Google Maps reviews will appear here when available. You can also ask our team for customer references.
INSURANCE QUESTIONS
Good questions.
Straight answers.
Should I call WeRoof before filing an insurance claim?
You can. We’ll inspect the roof and explain what we find, so you have more information before you speak with your insurance company. If there is active leaking or urgent damage, notify your insurer promptly and take reasonable steps to prevent further damage.
Will filing a roof insurance claim increase my premium?
It depends on your insurer, your policy, your claims history and state rules. Ask your insurance agent about possible effects before you file.
What if my insurance company denies my claim?
A denial doesn’t necessarily mean the roof needs no repairs. We can review the roofing findings with you, provide more contractor documentation when it’s warranted and talk through repair options. Coverage disputes belong with your insurer or an appropriately licensed professional.
Do I have to pay my deductible?
Yes. If your policy has a deductible, it is generally your responsibility. We do not promise to waive, absorb or disguise insurance deductibles.
Can I choose my own roofing contractor?
Generally, yes, subject to your policy and any program requirements. You don’t automatically have to use a contractor your insurance company recommends.
What if my roof is old?
Age alone doesn’t decide whether damage is covered. Policies may treat sudden storm damage differently from ordinary wear, deterioration or maintenance issues. We’ll help you understand the physical condition of your roof.
What if I don’t know when the storm happened?
Choose “I’m not sure” on the form. You don’t need an exact storm date to request an inspection.
Before you file a claim, know what you’re dealing with.
An inspection takes the guesswork out of storm damage: clear findings, photos and practical next steps.